What is the scope and market significance of the In Store Music Service Market?
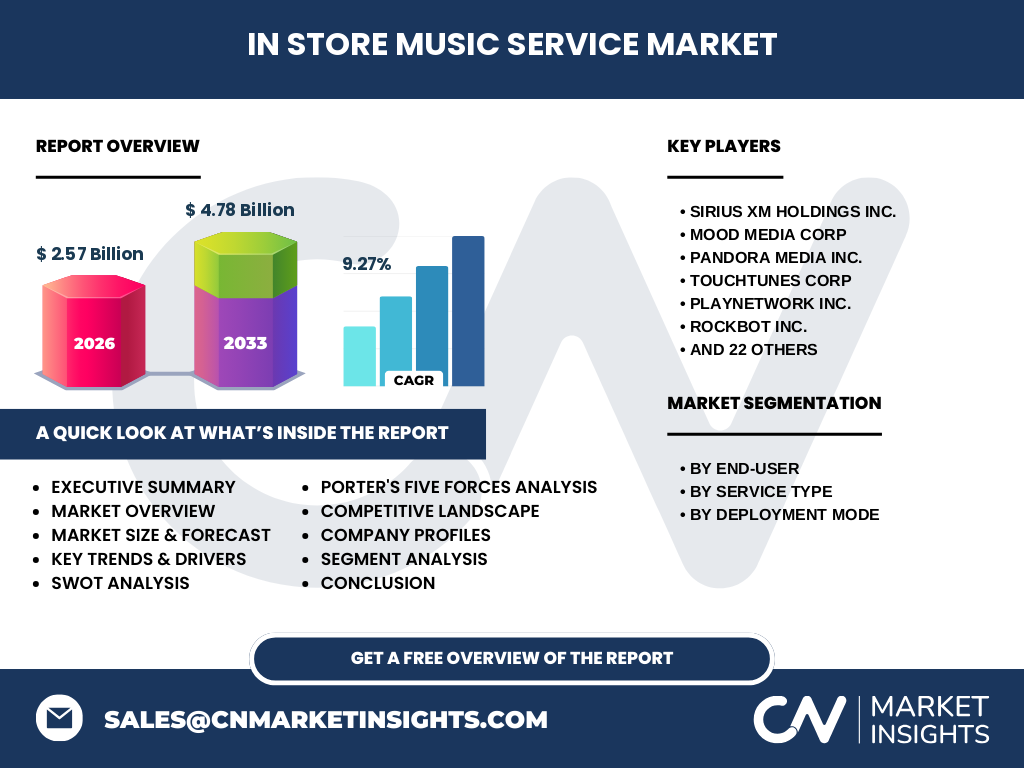
Our analysis indicates that the In Store Music Service Market reached a baseline valuation of 2.57 Billion. This ecosystem governs commercial audio licensing, curated background tracks, and dynamic point-of-sale messaging across brick-and-mortar storefronts, hospitality chains, and transit hubs.
What are the primary market drivers, restraints, and opportunities shaping the In Store Music Service Market industry trends?
The market is propelled by rising consumer demand for multi-sensory retail environments. However, stringent public performance rights fees from organizations like ASCAP and BMI act as key operational restraints. Significant growth opportunities lie in integrating AI-driven acoustic analytics to optimize foot traffic dwell times.
Emerging trends and growth patterns in the In Store Music Service Market
The shift toward hyper-localized audio branding allows enterprise chains to synchronize acoustic curation with regional inventory data. Vendors like Mood Media and Soundtrack Your Brand Sweden AB. leverage cloud architectures to deliver seamless, real-time playlist updates across global franchise networks.
How did the COVID-19 pandemic impact the In Store Music Service Market and what does the recovery trajectory look like?
Pandemic lockdowns caused unprecedented retail closures, temporarily depressing commercial audio subscriptions. As physical venues reopened, operators prioritized touchless, cloud-managed systems from innovators like Rockbot Inc. and SoundMachine to automate sanitation-compliant entertainment schedules and localized health announcements.
Competitive Benchmarking and Strategic Dynamics in the In Store Music Service Market
The competitive landscape features a mix of legacy enterprise giants like Sirius XM Holdings Inc. and agile digital disrupters such as Jukeboxy and Ambie Corp. Market concentration is intensifying as major players acquire niche sonic branding agencies to capture high-margin hospitality and luxury retail accounts.
Executive summary of key findings regarding the In Store Music Service Market
Our comprehensive In Store Music Service Market analysis projects robust expansion, driven by cloud deployment adoption and advanced audio analytics. Industry leaders are capitalizing on proprietary software integrations that bridge physical acoustic environments with digital consumer loyalty programs across multi-unit retail operations.
What is the projected In Store Music Service Market market size and growth forecast from 2027 to 2033?
The data suggests the sector will expand significantly, reaching 4.78 Billion by 2033. Driven by a robust compound annual growth rate of 9.27% from 2027 onward, this upward trajectory reflects accelerated enterprise investments in omnichannel sensory marketing strategies.
Segmentation analysis across end-users, service types, and deployment modes
Market segmentation spans end-users including Retail Stores, Restaurants, Shopping Malls, Hotels, and Other End-Users. Service types feature Background Music, In-Store Messaging, and Custom Music Solutions, while deployment relies on On-Premises hardware versus scalable Cloud architectures.
Geographic distribution and regional performance patterns
Regional performance varies based on local performance rights infrastructure and broadband penetration. North America commands the largest revenue share due to early adoption by national restaurant chains, while Asia-Pacific represents the fastest-growing frontier fueled by rapid shopping mall construction in metropolitan hubs.
In-depth regional review of key geographic territories
North American growth is underpinned by strict adherence to commercial licensing compliance enforced by organizations like SoundExchange. Meanwhile, European markets face fragmented copyright regulations across distinct member states, requiring localized curation platforms from providers such as Imagesound LTD and Soundreef LTD.
Company profiles and strategic positioning of leading industry participants
Industry leaders like PlayNetwork Inc. and TouchTunes Corp maintain strong holds through proprietary hardware and interactive jukebox ecosystems. Concurrently, software-first innovators such as Cloud Cover Media Inc. and Yodeck capture budget-conscious SMB segments with streamlined, web-managed subscription models.
Porter's Five Forces analysis of competitive intensity
Bargaining power of suppliers is moderate due to consolidated master recording rights held by major record labels. Threat of substitutes remains low given the legal prohibitions against using consumer-grade streaming accounts for commercial public performances in retail establishments.
SWOT analysis of the In Store Music Service Market industry landscape
Key strengths include high customer retention rates driven by recurring SaaS subscription models. Major weaknesses involve vulnerability to copyright infringement liabilities. Opportunities abound in programmatic audio advertising, while threats stem from complex international music licensing legal disputes.
Value chain analysis from raw copyright holders to end-users
The value chain flows from music publishers and independent artists through performing rights organizations, aggregator platforms like Qsic Pty LTD and Brandtrack Inc., and ultimately to commercial playback hardware installed in enterprise retail environments.
Investment insights and high-potential areas for capital allocation
High-potential investment targets include AI-driven acoustic personalization startups and firms possessing proprietary global licensing clearance frameworks. Investors should prioritize platforms offering seamless API integrations with existing enterprise point-of-sale and digital signage infrastructure.
Conclusion and core takeaways for industry stakeholders
The In Store Music Service Market is transitioning from passive audio playback to active, data-driven customer engagement. Stakeholders must embrace cloud agility and robust licensing compliance to capture shifting enterprise demand through 2033.
Research methodology used to triangulate market estimates
Our baseline estimates are rigorously triangulated by combining trade registry disclosures, primary stakeholder interviews with executives from firms like Retail Radio Inc. and Custom Channels.net LLC, and secondary macroeconomic indicators regarding retail construction spending.
Scope of the report, coverage parameters, and analytical limitations
This report covers global commercial audio deployments across designated vertical end-user segments from 2026 through 2033. Limitations include potential variance in localized public performance tariff enforcement across emerging economies and unregistered grey-market audio installations.
Recent developments, strategic partnerships, and product launches
Recent market momentum features strategic mergers and expanded API partnerships between digital signage providers and audio curators like StorePlay and Auracle Sound LTD. These alliances enable unified dashboard control for synchronized visual and acoustic merchandising campaigns.